 Broader markets witnessed intense sell off last week where Nifty fell 2.36% while Bank Nifty fell for almost 2.79% where sell off at Portfolio levels were much intense than it was actually seen on Index levels. As individual stocks seen upto 5-7% sell off in single session on Friday while last 15 sessions have almost wiped out 18-20% from Portfolio’s of major investors. Panic has set the investors mindset with pure chaos where Margin funded Accounts have shown some liquidation while long side derivatives positions faced short margin roll over issues. All this chaos combined created a panic sell off triggered by continuously rising Brent Crude Oil.
Despite the hints by by Honorable Finance Minister hinted possibility of LTCG / STT tax cut soon broader markets continued to witness the panic created by rising Brent Crude Oil & the Domino effect by the investors with excess margin exited their positions & the margin issue faced while roll over in derivatives while real fighter was “Nifty IT” which hit out target of 33000 but close with nominal gain of 0.22% last week.
In the meanwhile our FII vs Retail Short Long story remains intact where we have consistently mentioned about the longs & Shorts of Retail V/s FII’s which usually remains inversely proportionate & so far FII’s net shorts in index remains nearly at 2 years high at 3.20 lacs vs retails now reaching its 3-4 years levels of net longs at 2.58 lacs (both data as on 28/09/2026) while post the roll over FII’s were 2.67 lacs & retails were 2.24 Lacs but again both started inverse road map where FII’s were 3.07 lacs & Retail were 2.45 lacs while last week FII’s closed the week at 2.80 lacs shorts by FII’s while Retails longs remains at 2.15 lacs with net longs of FII’s now remains at 9-10%. We continue to expect once Retails to wind up its longs & FII’s may continue to cover the shorts while major market pressure levels to test on lower levels of 21900-22180 kind of levels.
FII’s have been very volatile since last 2 years where major selling has been done by them. As earlier anticipated the FII’s has initiated their buy in Financial Services sector, Healthcare, Consumer Services Sector & IT Sector & majorly all sectors rose back last week in which “Nifty IT” rose nearly 12% last week. Here we can have a brief look on the major inflow & outflow sector wise:
|
Equity |
Equity |
Equity |
Equity |
Equity |
Equity |
|
|---|---|---|---|---|---|---|
|
Sectors |
31/07/2026 |
15/08/2026 |
31/08/2026 |
15/09/2026 |
30/09/2026 |
15/10/2026 |
|
Automobile and Auto Components |
2372 |
4405 |
-1299 |
-2670 |
-3542 |
-6533 |
|
Capital Goods |
-3618 |
-1556 |
2162 |
-108 |
-1353 |
-3886 |
|
Chemicals |
532 |
315 |
543 |
228 |
-133 |
41 |
|
Construction |
-1602 |
-404 |
442 |
930 |
381 |
-1224 |
|
Construction Materials |
871 |
384 |
-250 |
-358 |
-847 |
-564 |
|
Consumer Durables |
4958 |
1472 |
2431 |
-397 |
-1508 |
-586 |
|
Consumer Services |
2840 |
3398 |
5019 |
422 |
1911 |
-1931 |
|
Diversified |
-1 |
-18 |
-4 |
-23 |
115 |
43 |
|
Fast Moving Consumer Goods |
478 |
-189 |
-1727 |
-2029 |
-972 |
-8172 |
|
Financial Services |
-2669 |
6535 |
3959 |
-6204 |
-6943 |
-8634 |
|
Forest Materials |
40 |
-9 |
-7 |
7 |
6 |
-50 |
|
Healthcare |
3654 |
2910 |
3021 |
2114 |
3 |
-5497 |
|
Information Technology |
3298 |
2530 |
1573 |
-960 |
-38 |
2599 |
|
Media, Entertainment & Publication |
24 |
-6 |
72 |
-93 |
31 |
252 |
|
Metals & Mining |
-1056 |
720 |
1087 |
-681 |
-2322 |
-3693 |
|
Oil, Gas & Consumable Fuels |
-513 |
490 |
-2251 |
-2385 |
-4469 |
-3680 |
|
Power |
-1596 |
-1164 |
-389 |
-1653 |
-570 |
-1732 |
|
Realty |
-279 |
-1014 |
420 |
-762 |
19 |
-578 |
|
Services |
-1 |
590 |
1193 |
905 |
1397 |
262 |
|
Telecommunication |
-3271 |
-3322 |
-1661 |
-991 |
-2423 |
-3928 |
|
Textiles |
206 |
1 |
-294 |
10 |
636 |
-59 |
|
Utilities |
-163 |
7 |
-38 |
194 |
-33 |
-34 |
|
Sovereign |
0 |
0 |
0 |
0 |
0 |
0 |
|
Others |
138 |
543 |
-992 |
388 |
-1091 |
-372 |
|
Grand Total |
4642 |
16618 |
13010 |
-14116 |
-21745 |
-47956 |
For overall scenario to consider we have below mentioned factors which created havoc & high volatility into the broader markets with the US-Iran war lying sideways. Rupee, crude oil, Dollar Index, etc. Let’s dig it out one by one:
- Rupee: Rupee as earlier anticipated 95 levels tested & went below we now continue to remain neutral as of now.
- Dollar Index: DXY standing right at resistance at 102 we may see a cool off towards 99 in coming weeks ahead.
- Brent Crude oil: Brent Crude Oil as earlier anticipated hit 116$ last week we now expect a cool off here from 120-123$ per barrel in the coming week ahead.
- FII’s Remained Covering Shorts: FII’s net longs & shorts now have once again shown drastic changes where net longs stand near to 9-10% while net shorts now remain at 2.73 lacs contacts. The expected short covering has now finally begun.
Nifty closed at 22600 with net loss of 2.36%. On FII’s from the saturation finally hit from 3.20 lacs net shorts which now remains at 2.80 Lacs. while DII’s added longs & Pro have added longs contracts last week while retail covered their longs to 2.15 lacs from 2.50 lacs earlier mentioned. We continue to expect the short covering to continue where FII’s may take their shorts to as low as 1.50 lacs contracts but this massive sell off may cool off from crucial support levels of 21900-22180 while immediate hurdle now lies at 23175 while any move above this could give us 23900 kind of levels. The major movement could get triggered by Banking & Financials Sector.
Bank Nifty remained under pressure due to rising Brent Crude Oil prices while in coming week ahead crucial support remains at 53000-53700 kind of levels while immediate potential upside remains at 56600-57000 in upcoming November series ahead with Festival season. The support may come from large-cap Private & Public Sector banks.
“Nifty IT” as earlier mentioned hit 33000 we now expect some profit booking towards 30500 from current levels of 31995.50.
Brent Crude Oil as earlier anticipated hit 116$ last week we now expect a cool off here from 120-123$ per barrel in the coming week ahead.
India remained on the higher ground on GDP data front where it achieved a milestone with historic growth rate of 7.80% in Q1, 8.20% in Q2 & 7.80% in Q3 of FY 25-26 completely mocking Trump’s “Dead Economy” jibe at its face where India remained on the Top-notch developing economy set for a target of $25 Trillion economy by 2047 on track. However, chairman of Reliance Industries Limited Mr. Mukesh Ambani said in its latest AGM last week that India has the capacity to achieve 10% GDP growth annually which once again has set another long-lasting futuristic goal for the entire economy.
FII & DII’s monthly data so far in the FY 2026-27 has been interesting where FII’s bought in few months initially then abstain from buying or remained to being on the sell side while DII’s remained the biggest supporter of the broader markets. The data below mentioned:
|
Month |
FII |
DII |
|---|---|---|
|
Apr’26 |
-70,135.46 |
51,063.87 |
|
May’26 |
-46,430.42 |
57,947.52 |
|
June’26 |
-49,028.63 |
85,800.14 |
|
July’26 |
-5,778.99 |
35,099.25 |
|
Aug’26 |
454.04 |
53,679.27 |
|
Sept’26 |
-44,012.82 |
76,030.29 |
|
Oct’26 |
-51,466.38 |
59,110.32 |
|
TOTAL |
-266,398.66 |
418,730.66 |
The Indian Equity markets have gained many recent news item where major of the news items are mentioned below:
- Rupee: Rupee as earlier anticipated 95 levels tested & went below we now continue to remain neutral as of now.
- Dollar Index: DXY standing right at resistance at 102 we may see a cool off towards 99 in coming weeks ahead.
- Brent Crude oil: Brent Crude Oil as earlier anticipated hit 116$ last week we now expect a cool off here from 120-123$ per barrel in the coming week ahead.
On the other side FII’s net longs now near to 9-10% & a recovery is possible towards 17% followed by 27% till the coming weekend which continuously signifies & now support could be at 21900-22180 in Nifty.
In the wholesome broader markets witnessed some key events & their outcomes last week which are described as follows:
Domestic News:
- Fairfax’s Discounted IDBI Bank Stake Sale: The Union Cabinet approved a ₹52,878-crore stake sale of IDBI Bank to Fairfax Financial. However, because the sale was transacted at a discount, IDBI shares plunged 8%, creating immediate pricing headwinds for the public sector banking ecosystem.
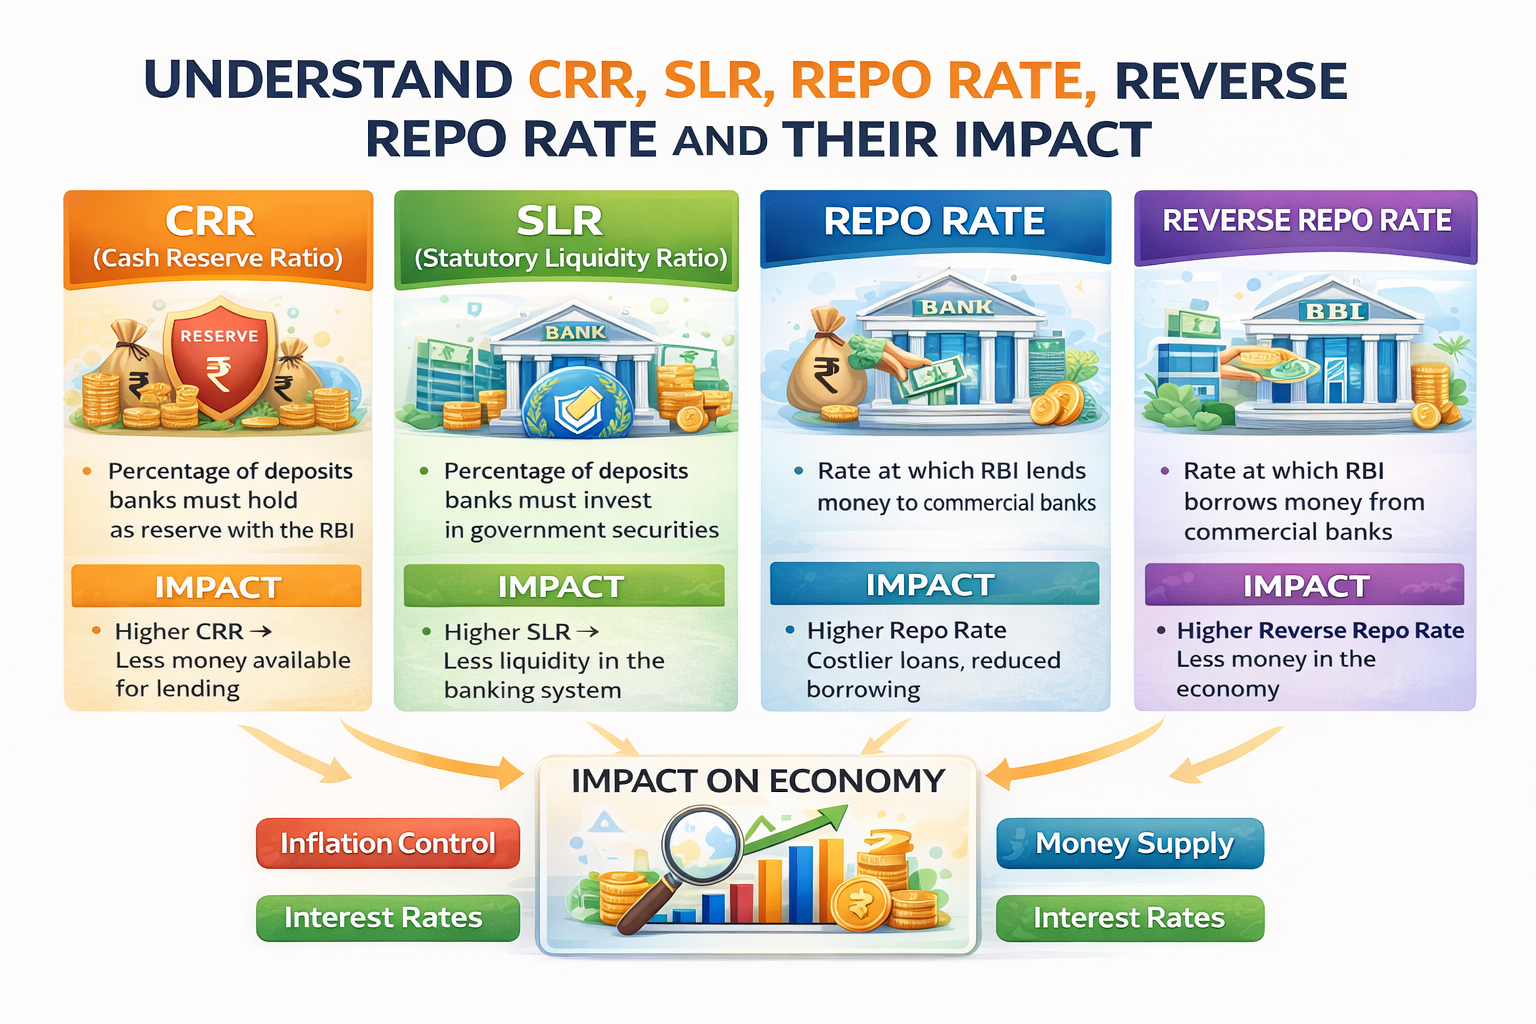
- Hawkish Monetary Outlook: Following the RBI’s recent 0.25% repo rate hike to combat El Niño‑related inflation pressures, bond yields remain sensitive. Corporate commentary on margins and lending rates will be tightly parsed by financial investors next week.
- LTCG and STT Review Openings: Finance Minister Nirmala Sitharaman stated that the government is open to stakeholder views on reforming the Long-Term Capital Gains (LTCG) tax and the Securities Transaction Tax (STT). This triggered an optimistic surge on Dalal Street following massive Foreign Portfolio Investor (FPI) outflows.
- Current Holding Tax Burden: As of current regulations, LTCG on listed equities exceeding ₹1.25 lakh annually is taxed at 5%, while Short-Term Capital Gains (STCG) remain at 20%. Recent budget updates also hiked STT on equity futures to 0.05%.
- Union Minister Nitin Gadkari has urged sugar mills to shift focus from plain sugar to high-value by-products like ethanol, compressed bio-gas (CBG), and bio-manure, calling the future of standalone sugar production “mediocre.
- The government’s credit guarantee cover for MSME invoice financing on TReDS is now live, and M1Xchange has completed the first transaction under this mechanism
- Commerce Minister Piyush Goyal has announced that about 1,000 trained personnel will be deployed to support exporters at district and state levels, with outreach and handholding in regional languages
- India has launched an anti-dumping probe into imports of glycine from China after domestic producer Avid Organics filed a complaint alleging injury from dumped shipments.
International news:
- The Unraveling AI Hardware Trade: Market leaders like Nvidia, Intel, and Micron suffered sharp weekly contractions as investors questioned whether hyper-scaled AI infrastructure investments will materialize into near-term profitability.
- Relative Rotation into Indian IT Exporters: In a massive divergence, global fund managers are treating the AI hardware slump as a catalyst to enter defensive international software plays. This fundamental rotation is directly fueling the multi-year weekly high witnessed across the Nifty IT Index.
- A “Live” Fed Rate Hike Call for October: While central bank watchers originally anticipated a pause, a hotter-than-expected 3.7% US CPI print has turned the Federal Reserve’s October policy meeting into a highly contentious, live decision. The threat of another interest rate hike under Chairman Kevin Warsh will restrict foreign fund allocation to developing nations like India.
- Crude Oil Surging Past $109/Barrel: Driven by supply risks and geopolitical instabilities in the Middle East, Brent crude oil futures climbed over 3.5% to hit $109.55 per barrel. As a country that imports over 80% of its crude, sustained triple-digit oil prices pose an immediate threat to India’s fiscal deficit and margin outlook for paint and tire firms.
- The Strong Dollar Index and Weakening Rupee: The US Dollar Index held firm near 101.80, piling pressure on emerging market currencies. The Indian Rupee touched record lows of 76 per USD, which will likely trigger continued defensive hedging by Indian information technology and pharmaceutical exporters.
- Sustained Foreign Portfolio Investor (FPI) Outflows: Aggressive safe-haven rotation pulled international capital away from Asian emerging equity blocks, leading to over ₹89,000 crores in net FII selling over the last month. Dalal Street will heavily depend on domestic mutual fund inflows next week to absorb further global liquidations.
- High-Stakes US Mega-Cap Earnings Approaching: Tech heavyweights like Meta Platforms, Tesla, and Netflix are scheduled to report their quarterly earnings in the coming week. Their corporate outlook statements will dictate whether global market sentiment stabilizes or enters a deeper tech correction.
- The MSCI Indonesia Warning Shot: Index provider MSCI’s moves toward potentially expelling Indonesia from global standard indexes triggered trading halts on the Jakarta exchange and jittered broader Southeast Asian portfolios. This has put institutional risk managers on high alert regarding regulatory compliance across emerging Asian markets.
Nifty closed at 22600 with net loss of 2.36%. On FII’s from the saturation finally hit from 3.20 lacs net shorts which now remains at 2.80 Lacs. while DII’s added longs & Pro have added longs contracts last week while retail covered their longs to 2.15 lacs from 2.50 lacs earlier mentioned. We continue to expect the short covering to continue where FII’s may take their shorts to as low as 1.50 lacs contracts but this massive sell off may cool off from crucial support levels of 21900-22180 while immediate hurdle now lies at 23175 while any move above this could give us 23900 kind of levels. The major movement could get triggered by Banking & Financials Sector.
Bank Nifty remained under pressure due to rising Brent Crude Oil prices while in coming week ahead crucial support remains at 53000-53700 kind of levels while immediate potential upside remains at 56600-57000 in upcoming November series ahead with Festival season. The support may come from large-cap Private & Public Sector banks.
“Nifty IT” as earlier mentioned hit 33000 we now expect some profit booking towards 30500 from current levels of 31995.50.
In Sensex crucial supports now remain within range of 71000-71500 range while immediate target could be towards 76000 kind of levels.
Nifty Financials may find its crucial support levels now at 24000 kind of levels upside immediate target still lies at 26500-26700 kind of levels.
As of January 2026 the number of Demat Accounts has hit whopping 22.9 crores this not only helps the capital markets directly but also directly to Equity investments.
The monthly SIP in Indian markets have now increased to All Time High of Rs. 32,087 cr. per month as on March 2026.
Brief Levels of Nifty / Sensex/ Bank Nifty / Nifty Financials / Nifty IT:
Nifty CMP: 22600
Nifty Potential Upside: 23175-23900
Nifty Immediate Crucial Support: 21900-22180
Sensex CMP: 73123.83
Sensex Potential Upside: 76000
Sensex Immediate Crucial Support: 71000-71500
Bank Nifty CMP: 54287.35
Bank Nifty Immediate Upside: 56600-57000
Bank Nifty Immediate Crucial Support: 53000-53700
Nifty Financial CMP: 24403
Nifty Financial Immediate Target: 26500-26700
Nifty Financial Immediate Crucial Support: 24000
Nifty IT CMP: 31995.50
Nifty IT Immediate Downside Target: 30500
Nifty IT Immediate Hurdle: 33000-33700
About the Author:
Mr. Vishal Gupta a SEBI Registered Research Analyst is the founder of “VG STOCK RESEARCH”, founder of “THE ANALYSIS ROOM”, a writer & an advisor having rich experience in Indian Equity Markets who has spent years comprehending an industry wide shift and risk management with more than 14+ years exploring in depth analysis of the Equity & Derivatives.
He has also been into teaching Fundamental Analysis for quite some time giving investors/traders comprehensive knowledge & skills of Indian Equity Markets.
Email I’d: contact@vgstockresearch.com
Contact: +91-9953934544
Website: https://vgstockresearch.com/
SEBI Reg. No.: INH1000079