 As Honorable Finance Minister hinted possibility of LTCG / STT tax cut soon the Bulls roared back on Dalaal Street with strong close above 23000 at 23146.15 while Bank Nifty remained less attractive with nominal gain of 1.06% for the week but gave a bullish closing at 55844 while real fighter was “Nifty IT” which rose by 11.72% & gave a decisive close at 31924.10 completed our target of 32000.
In the meanwhile our FII vs Retail Short Long story remains intact where we have consistently mentioned about the longs & Shorts of Retail V/s FII’s which usually remains inversely proportionate & so far FII’s net shorts in index remains nearly at 2 years high at 3.20 lacs vs retails now reaching its 3-4 years levels of net longs at 2.58 lacs (both data as on 28/09/2026) while post the roll over FII’s were 2.67 lacs & retails were 2.24 Lacs but again both started inverse road map where FII’s were 3.07 lacs & Retail were 2.45 lacs while last week FII’s closed the week at 2.73 lacs shorts by FII’s while Retails longs remains at 2.20 lacs with net longs of FII’s rose back from 8% to now 11-12%. We continue to expect once Retails to wind up its longs & FII’s may continue to cover the shorts the market has already bottomed out & strong upward momentum may emerger which may take an immediate target towards 23500-24000-24300 kind of levels.
FII’s have been very volatile since last 2 years where major selling has been done by them. As earlier anticipated the FII’s has initiated their buy in Financial Services sector, Healthcare, Consumer Services Sector & IT Sector & majorly all sectors rose back last week in which “Nifty IT” rose nearly 12% last week. Here we can have a brief look on the major inflow & outflow sector wise:
|
Equity |
Equity |
Equity |
Equity |
Equity |
|
|---|---|---|---|---|---|
|
Sectors |
31/07/2026 |
15/08/2026 |
31/08/2026 |
15/09/2026 |
30/09/2026 |
|
Automobile and Auto Components |
2372 |
4405 |
-1299 |
-2670 |
-3542 |
|
Capital Goods |
-3618 |
-1556 |
2162 |
-108 |
-1353 |
|
Chemicals |
532 |
315 |
543 |
228 |
-133 |
|
Construction |
-1602 |
-404 |
442 |
930 |
381 |
|
Construction Materials |
871 |
384 |
-250 |
-358 |
-847 |
|
Consumer Durables |
4958 |
1472 |
2431 |
-397 |
-1508 |
|
Consumer Services |
2840 |
3398 |
5019 |
422 |
1911 |
|
Diversified |
-1 |
-18 |
-4 |
-23 |
115 |
|
Fast Moving Consumer Goods |
478 |
-189 |
-1727 |
-2029 |
-972 |
|
Financial Services |
-2669 |
6535 |
3959 |
-6204 |
-6943 |
|
Forest Materials |
40 |
-9 |
-7 |
7 |
6 |
|
Healthcare |
3654 |
2910 |
3021 |
2114 |
3 |
|
Information Technology |
3298 |
2530 |
1573 |
-960 |
-38 |
|
Media, Entertainment & Publication |
24 |
-6 |
72 |
-93 |
31 |
|
Metals & Mining |
-1056 |
720 |
1087 |
-681 |
-2322 |
|
Oil, Gas & Consumable Fuels |
-513 |
490 |
-2251 |
-2385 |
-4469 |
|
Power |
-1596 |
-1164 |
-389 |
-1653 |
-570 |
|
Realty |
-279 |
-1014 |
420 |
-762 |
19 |
|
Services |
-1 |
590 |
1193 |
905 |
1397 |
|
Telecommunication |
-3271 |
-3322 |
-1661 |
-991 |
-2423 |
|
Textiles |
206 |
1 |
-294 |
10 |
636 |
|
Utilities |
-163 |
7 |
-38 |
194 |
-33 |
|
Sovereign |
0 |
0 |
0 |
0 |
0 |
|
Others |
138 |
543 |
-992 |
388 |
-1091 |
|
Grand Total |
4642 |
16618 |
13010 |
-14116 |
-21745 |
For overall scenario to consider we have below mentioned factors which created havoc & high volatility into the broader markets with the US-Iran war lying sideways. Rupee, crude oil, Dollar Index, etc. Let’s dig it out one by one:
- Rupee: Rupee as earlier anticipated 95 levels almost tested we now remain neutral as of now.
- Dollar Index: DXY standing right at resistance at 102 we may see a cool off towards 99 in coming weeks ahead.
- Brent Crude oil: Brent Crude Oil hit 110$ per barrel a red flag for the coming week it may hit 116$ per barrel while it may become weak below 102$ till then we remain neutral.
- FII’s Remained Covering Shorts: FII’s net longs & shorts now have once again shown drastic changes where net longs stand near to 11-12% while net shorts now remain at 2.73 lacs contacts. The expected short covering has now finally began.
Nifty closed at 22520.45 with net gain of 2.78%%. On FII’s from the saturation finally hit from 3.20 lacs net shorts which now remains at 2.73 Lacs. while DII’s added longs & Pro have covered longs contracts almost in last week while retail covered their longs to 2.20 lacs from 2.50 lacs earlier mentioned. We continue to expect the short covering to continue where FII’s may take their shorts to as low as 1.50 lacs contracts in the coming weeks ahead which may take Nifty target towards 23500-24000-24300 kind of levels while crucial supports now shifted higher within the bigger range of 22500-22700. The major movement could continue to get triggered by Banking & Financials Sector followed by IT & Consumer Durables goods sector.
However, Bank Nifty underperformed last week with only 1% positive momentum while in coming week ahead crucial support remains at 55000-55500 kind of levels while immediate potential upside remains at 56600-57000 & 58000-58700 in upcoming Festival season. The support may come from large-cap Private & Public Sector banks.
“Nifty IT” sector has shown immense response by FII’s with consistent buying in last 45 our mentioned target of 32000 came it may marginal head higher at 33000 & may show some cool off now while crucial supports now remain at 30000.
Brent Crude Oil hit 110$ per barrel a red flag for the coming week it may hit 116$ per barrel while it may become weak below 102$ till then we remain neutral.
India remained on the higher ground on GDP data front where it achieved a milestone with historic growth rate of 7.80% in Q1, 8.20% in Q2 & 7.80% in Q3 of FY 25-26 completely mocking Trump’s “Dead Economy” jibe at its face where India remained on the Top-notch developing economy set for a target of $25 Trillion economy by 2047 on track. However, chairman of Reliance Industries Limited Mr. Mukesh Ambani said in its latest AGM last week that India has the capacity to achieve 10% GDP growth annually which once again has set another long-lasting futuristic goal for the entire economy.
FII & DII’s monthly data so far in the FY 2026-27 has been interesting where FII’s bought in few months initially then abstain from buying or remained to being on the sell side while DII’s remained the biggest supporter of the broader markets. The data below mentioned:
|
Month |
FII |
DII |
|---|---|---|
|
Apr’26 |
-70,135.46 |
51,063.87 |
|
May’26 |
-46,430.42 |
57,947.52 |
|
June’26 |
-49,028.63 |
85,800.14 |
|
July’26 |
-5,778.99 |
35,099.25 |
|
Aug’26 |
454.04 |
53,679.27 |
|
Sept |
-44,012.82 |
76,030.29 |
|
Oct |
-48,769.01 |
48,168.13 |
|
TOTAL |
-263,701.29 |
407,788.47 |
The Indian Equity markets have gained many recent news item where major of the news items are mentioned below:
- Rupee: Rupee as earlier anticipated 95 levels almost tested we now remain neutral as of now.
- Dollar Index: DXY standing right at resistance at 102 we may see a cool off towards 99 in coming weeks ahead.
- Brent Crude oil: Brent Crude Oil hit 110$ per barrel a red flag for the coming week it may hit 116$ per barrel while it may become weak below 102$ till then we remain neutral.
On the other side FII’s net longs now near to 11-12% & a recovery is possible towards 17% followed by 27% till the coming weekend which continuously signifies & now support could be at 22500-22700 in Nifty.
In the wholesome broader markets witnessed some key events & their outcomes last week which are described as follows:
Domestic News:
- The Mega $3.2 Billion Jio Platforms IPO: The record-breaking $3.2 billion IPO of Jio Platforms is officially opening for subscription on October 21. The gray market premium (GMP) has already surged 84% in two weeks, and this mega-flotation is expected to absorb significant system liquidity next week.
- Fairfax’s Discounted IDBI Bank Stake Sale: The Union Cabinet approved a ₹52,878-crore stake sale of IDBI Bank to Fairfax Financial. However, because the sale was transacted at a discount, IDBI shares plunged 8%, creating immediate pricing headwinds for the public sector banking ecosystem.
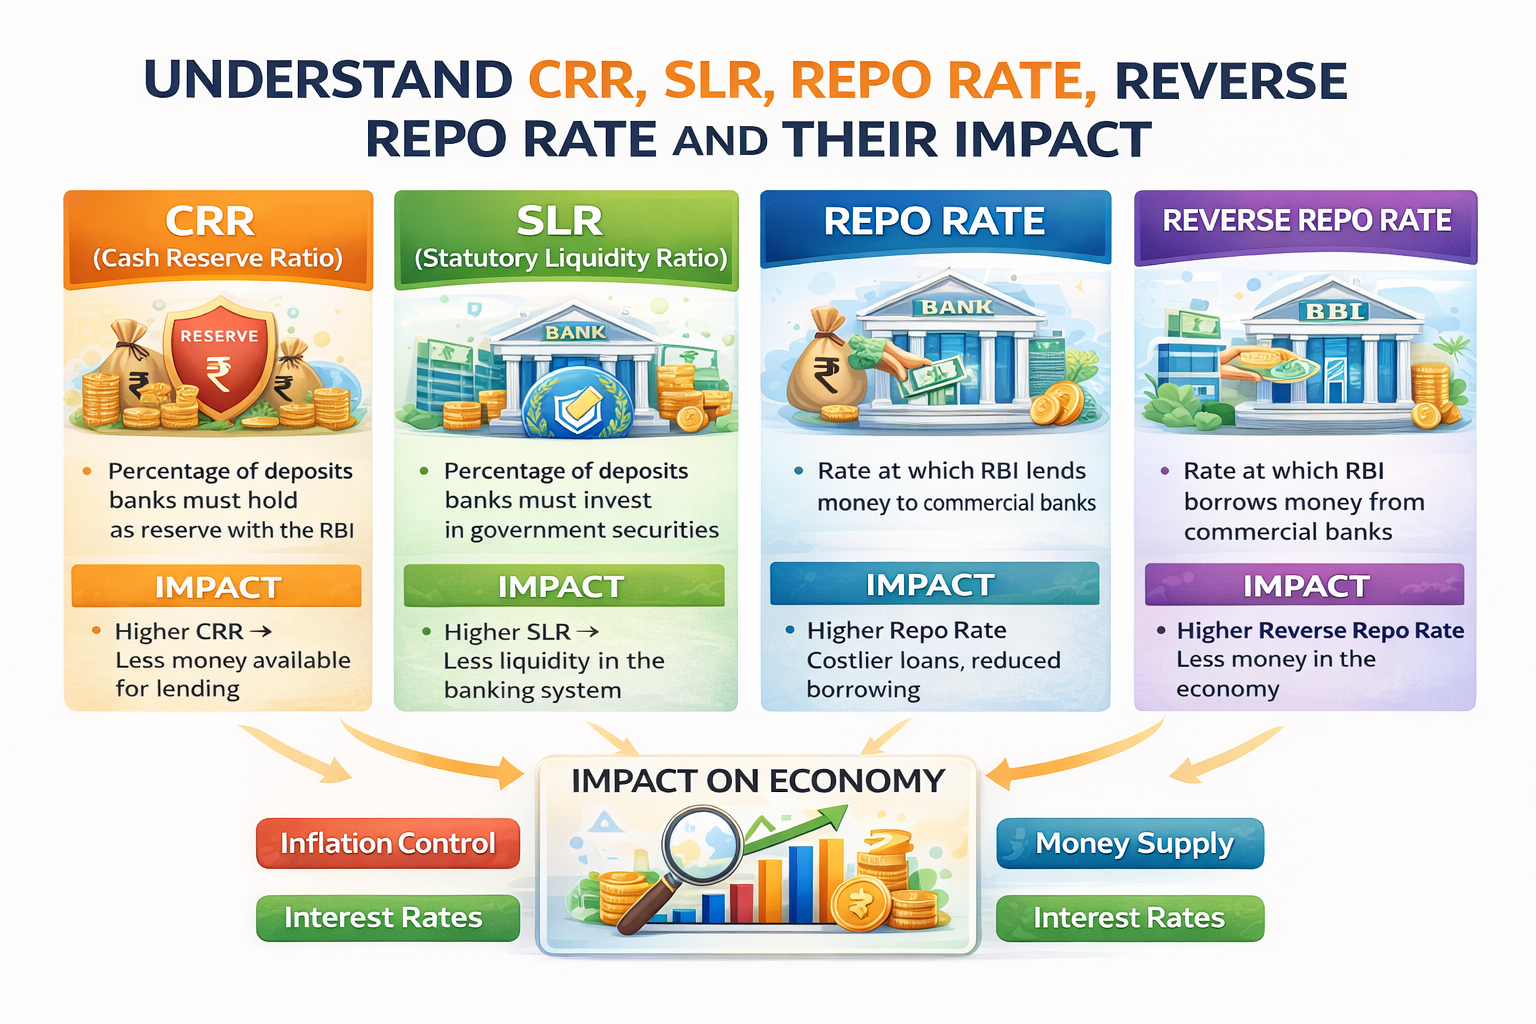
- Hawkish Monetary Outlook: Following the RBI’s recent 0.25% repo rate hike to combat El Niño‑related inflation pressures, bond yields remain sensitive. Corporate commentary on margins and lending rates will be tightly parsed by financial investors next week.
- LTCG and STT Review Openings: Finance Minister Nirmala Sitharaman stated that the government is open to stakeholder views on reforming the Long-Term Capital Gains (LTCG) tax and the Securities Transaction Tax (STT). This triggered an optimistic surge on Dalal Street following massive Foreign Portfolio Investor (FPI) outflows.
- Current Holding Tax Burden: As of current regulations, LTCG on listed equities exceeding ₹1.25 lakh annually is taxed at 5%, while Short-Term Capital Gains (STCG) remain at 20%. Recent budget updates also hiked STT on equity futures to 0.05%.
- Union Minister Nitin Gadkari has urged sugar mills to shift focus from plain sugar to high-value by-products like ethanol, compressed bio-gas (CBG), and bio-manure, calling the future of standalone sugar production “mediocre.
- The government’s credit guarantee cover for MSME invoice financing on TReDS is now live, and M1Xchange has completed the first transaction under this mechanism
- Commerce Minister Piyush Goyal has announced that about 1,000 trained personnel will be deployed to support exporters at district and state levels, with outreach and handholding in regional languages
- India has launched an anti-dumping probe into imports of glycine from China after domestic producer Avid Organics filed a complaint alleging injury from dumped shipments.
- RBI says FCNR(B)-linked PSL exemptions will apply only to deposits mobilized until August 31.
- International news:
- Wall Street’s Steepest Tech Drop Since June: The tech-heavy Nasdaq Composite plunged 2.1% on Friday to cap its worst weekly performance since early summer. If global tech stocks continue to falter, it could trigger generalized risk-off sentiment in Indian growth sectors.
- The Unraveling AI Hardware Trade: Market leaders like Nvidia, Intel, and Micron suffered sharp weekly contractions as investors questioned whether hyper-scaled AI infrastructure investments will materialize into near-term profitability.
- Relative Rotation into Indian IT Exporters: In a massive divergence, global fund managers are treating the AI hardware slump as a catalyst to enter defensive international software plays. This fundamental rotation is directly fueling the multi-year weekly high witnessed across the Nifty IT Index.
- A “Live” Fed Rate Hike Call for October: While central bank watchers originally anticipated a pause, a hotter-than-expected 3.7% US CPI print has turned the Federal Reserve’s October policy meeting into a highly contentious, live decision. The threat of another interest rate hike under Chairman Kevin Warsh will restrict foreign fund allocation to developing nations like India.
- Crude Oil Surging Past $109/Barrel: Driven by supply risks and geopolitical instabilities in the Middle East, Brent crude oil futures climbed over 3.5% to hit $109.55 per barrel. As a country that imports over 80% of its crude, sustained triple-digit oil prices pose an immediate threat to India’s fiscal deficit and margin outlook for paint and tire firms.
- The Strong Dollar Index and Weakening Rupee: The US Dollar Index held firm near 101.80, piling pressure on emerging market currencies. The Indian Rupee touched record lows of 76 per USD, which will likely trigger continued defensive hedging by Indian information technology and pharmaceutical exporters.
- Sustained Foreign Portfolio Investor (FPI) Outflows: Aggressive safe-haven rotation pulled international capital away from Asian emerging equity blocks, leading to over ₹89,000 crores in net FII selling over the last month. Dalal Street will heavily depend on domestic mutual fund inflows next week to absorb further global liquidations.
- High-Stakes US Mega-Cap Earnings Approaching: Tech heavyweights like Meta Platforms, Tesla, and Netflix are scheduled to report their quarterly earnings in the coming week. Their corporate outlook statements will dictate whether global market sentiment stabilizes or enters a deeper tech correction.
- The MSCI Indonesia Warning Shot: Index provider MSCI’s moves toward potentially expelling Indonesia from global standard indexes triggered trading halts on the Jakarta exchange and jittered broader Southeast Asian portfolios. This has put institutional risk managers on high alert regarding regulatory compliance across emerging Asian markets.
- Gold Defensively Hovers Near Record Highs: Geopolitical friction and stubborn global inflation pushed gold futures upward to $4,190 an ounce. A prolonged flight to safety in bullion usually signals institutional hesitation toward equity allocations, capping aggressive multi-day rallies.
Nifty closed at 22520.45 with net gain of 2.78%%. On FII’s from the saturation finally hit from 3.20 lacs net shorts which now remains at 2.73 Lacs. while DII’s added longs & Pro have covered longs contracts almost in last week while retail covered their longs to 2.20 lacs from 2.50 lacs earlier mentioned. We continue to expect the short covering to continue where FII’s may take their shorts to as low as 1.50 lacs contracts in the coming weeks ahead which may take Nifty target towards 23500-24000-24300 kind of levels while crucial supports now shifted higher within the bigger range of 22500-22700. The major movement could continue to get triggered by Banking & Financials Sector followed by IT & Consumer Durables goods sector.
However, Bank Nifty underperformed last week with only 1% positive momentum while in coming week ahead crucial support remains at 55000-55500 kind of levels while immediate potential upside remains at 56600-57000 & 58000-58700 in upcoming Festival season. The support may come from large-cap Private & Public Sector banks.
“Nifty IT” sector has shown immense response by FII’s with consistent buying in last 45 our mentioned target of 32000 came it may marginal head higher at 33000 & may show some cool off now while crucial supports now remain at 30000.
In Sensex crucial supports now remain within range of 73000-74000 range while immediate target could be towards 78000 kind of levels.
Nifty Financials may find its crucial support levels now at 25000 kind of levels upside immediate target still lies at 27200 kind of levels.
As of January 2026 the number of Demat Accounts has hit whopping 22.9 crores this not only helps the capital markets directly but also directly to Equity investments.
The monthly SIP in Indian markets have now increased to All Time High of Rs. 32,087 cr. per month as on March 2026.
Brief Levels of Nifty / Sensex/ Bank Nifty / Nifty Financials / Nifty IT:
Nifty CMP: 23146.15
Nifty Potential Upside: 23500-24000-24300
Nifty Immediate Crucial Support: 22500-22700
Sensex CMP: 74729.30
Sensex Potential Upside: 78000
Sensex Immediate Crucial Support: 73000-74000
Bank Nifty CMP: 55844
Bank Nifty Immediate Upside: 56600-57000 / 58000-58700 (As the case may be)
Bank Nifty Immediate Crucial Support: 55000-55500
Nifty Financial CMP: 25387.10
Nifty Financial Immediate Target: 27200\
Nifty Financial Immediate Crucial Support: 25000
Nifty IT CMP: 31924.10
Nifty IT Immediate Target: 33000
Nifty IT Immediate Crucial Support: 30000
About the Author:
Mr. Vishal Gupta a SEBI Registered Research Analyst is the founder of “VG STOCK RESEARCH”, founder of “THE ANALYSIS ROOM”, a writer & an advisor having rich experience in Indian Equity Markets who has spent years comprehending an industry wide shift and risk management with more than 14+ years exploring in depth analysis of the Equity & Derivatives.
He has also been into teaching Fundamental Analysis for quite some time giving investors/traders comprehensive knowledge & skills of Indian Equity Markets.
Email I’d: contact@vgstockresearch.com
Contact: +91-9953934544
Website: https://vgstockresearch.com/
SEBI Reg. No.: INH1000079